Meet our partner
Buying a golf home in the UAE with a mortgage brings the property, the lender and the payment timetable into one plan. Whether it is a finished villa beside an established course or a new home due for handover in a few years, the finance questions are best answered before a reservation is signed.
Golf Homes International helps clients find and assess golf and lifestyle property across the UAE. When a purchase will involve mortgage finance, we can introduce SPF Private Clients (SPF), our mortgage partner in the UAE.
For off-plan buyers, that means shortlisting developments that match your budget and timescale, checking the payment plan against your own funds before you reserve, and staying with you through the instalments to handover. SPF works alongside us on the finance, so the property and the mortgage are planned together.
Our partnership with SPF
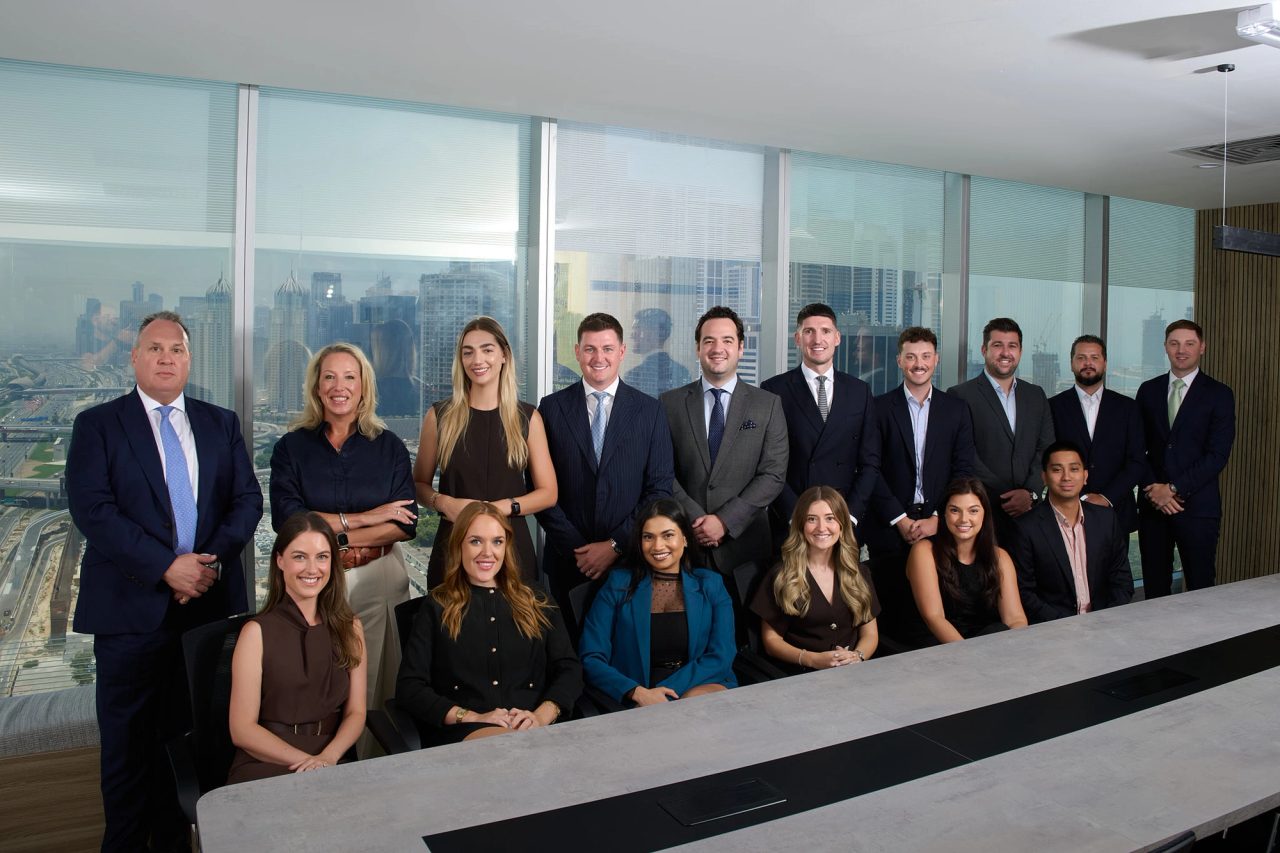
SPF is a mortgage brokerage and part of Howden, the global insurance broker. Its UAE business, SPF Private Clients Mortgage Brokerage LLC, discusses each client's requirements, explores mortgage options, outlines its recommendations and supports the application to the lender. In the UK, SPF Private Clients Limited advises on UK mortgages, including raising money against a UK home.
We can introduce clients to SPF while they are setting a budget, weighing up a new-build purchase or preparing an offer. We remain responsible for guiding the property search, while SPF provides its own mortgage advice and handles the application with the lender.
An early introduction gives clients time to understand what borrowing may be realistic, which documents they will need and how finance fits the purchase timetable.
The partner insight
Whether you buy a completed home or off-plan, the timing of each payment decides how much you fund yourself and when any mortgage is needed. This insight sets out what a UAE bank can lend, works through one completed home and two off-plan purchases from homes we offer, then sets out the steps and questions that matter.
A completed home can be valued as it stands. An off-plan home is paid for in stages while it is built, so the questions about valuation, timing and lender assessment are quite different.
- Completed resale
- The home already exists, so it can be valued and assessed as it stands. Allow for valuation, lender approval and the transfer timetable before agreeing a completion date.
- Off-plan
- Payments are often staged through construction. Ask whether and when a lender would consider finance, how staged payments are funded before then and what happens if circumstances change before handover.
What a UAE bank can lend
The Central Bank of the UAE sets the maximum a bank may lend against a home. These are ceilings, not entitlements: each bank can apply stricter limits, and the amount you are offered depends on your income, your commitments and the bank's independent valuation, which may be lower than the price.
- For an expatriate buying a first home to live in: up to 80% of value for homes up to AED 5m, and up to 70% above AED 5m.
- For a second home or investment property: up to 60% of value.
- For any off-plan property, whoever the buyer: up to 50% of value.
The 80% and 70% limits are for a first home you will live in, so they generally apply if you live in, or are moving to, the UAE. For buyers who live outside the UAE, SPF says finance is available subject to individual assessment, up to 60% of value. If you are buying from abroad, plan on 60%.
Banks also test affordability. All your debt repayments together can be no more than half of your gross income, tested at an interest rate two to four percentage points higher. For expatriates, the loan can be no more than seven times annual income, over a maximum of 25 years. The deposit should come from your own resources, not from other borrowing, and on an off-plan home your own money is paid to the developer before the bank pays its share.
On top of the deposit, Dubai's property transfer fee is 4% of the price, and registering a mortgage costs 0.25% of the loan plus title and trustee fees. In Abu Dhabi, DARI lists a registration fee of 2% of the contract value plus an AED 875 e-services fee.
Three purchases, worked through
One completed villa and two off-plan developments we offer show how differently the money can flow: when you pay, how much comes from your own funds, and what a lender might be asked to cover.
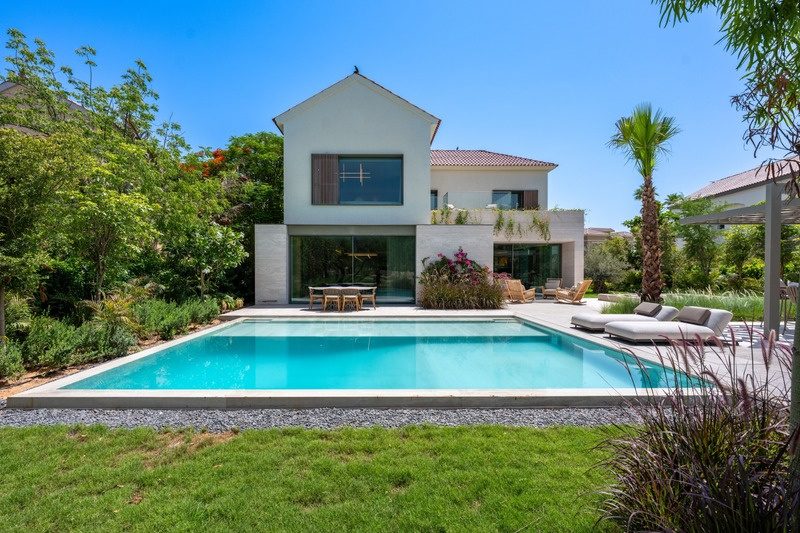
This completed five-bedroom villa on Redwood Avenue has 15,810 sq ft of built-up space over three levels, on an 11,281 sq ft plot with panoramic golf-course views. It is fully furnished and offered at AED 22.5m.
Because the home already exists, there are no instalments. The balance is paid at transfer, so any finance has to be in place by then. As a home above AED 5m, the most a bank could lend is 60%, or AED 13.5m, if you live abroad or it will be a second home, leaving a deposit of AED 9m. If you are moving to the UAE and it will be your main home, the limit is 70%, or AED 15.75m. The transfer fee at 4% adds AED 900,000. The conversation with SPF comes before you make an offer: what a lender may be prepared to lend on your circumstances, how the valuation could affect that figure, and how the offer, the finance and the transfer date line up.
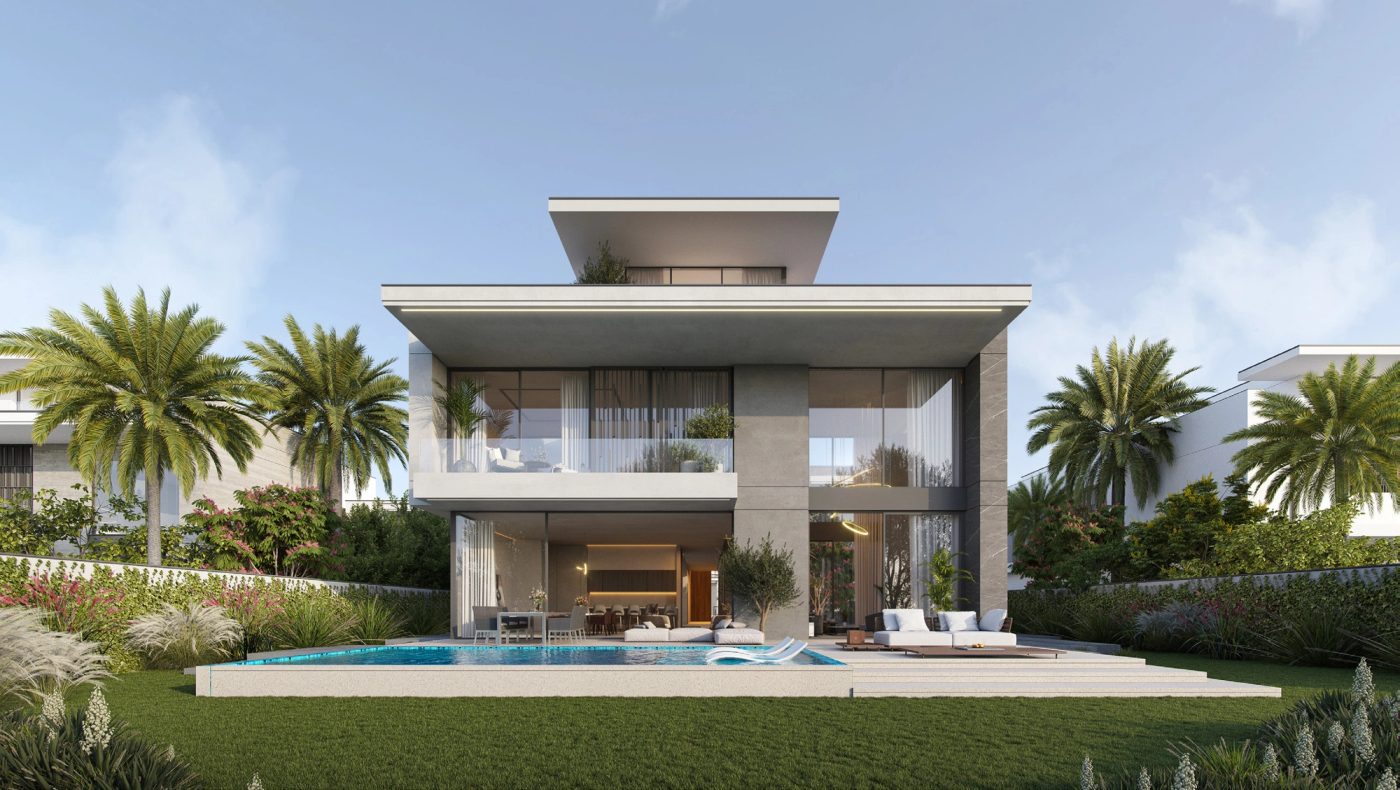
Cedarwood Estates South is a collection of 74 four-, five- and six-bedroom golf villas in Jumeirah Golf Estates, Dubai, with four-bedroom villas from AED 13.35m and handover expected in Q1 2029. The published plan is 10% on booking, four further 10% instalments between December 2026 and July 2028, and 50% at handover.
On a four-bedroom villa at AED 13.35m, that is AED 1.335m at booking and at each instalment, AED 6.675m before handover, and the same again at completion. Half the price is paid from your own funds by July 2028, so the budgeting conversation needs to happen before you book. Off-plan loans are capped at 50% of value, so the plan sits right at that limit. Ask SPF whether finance could meet part of the handover balance, and how a lender would assess the home once it is complete.
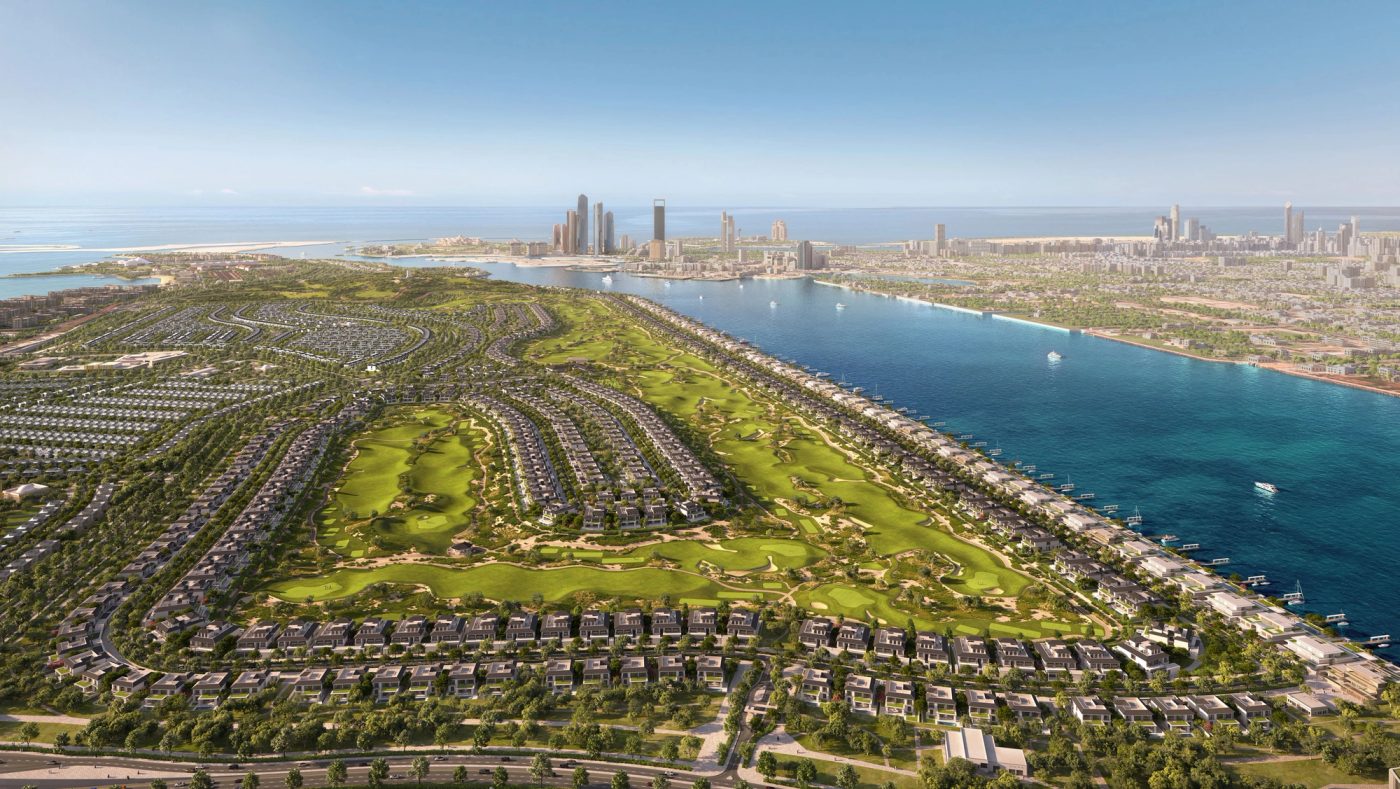
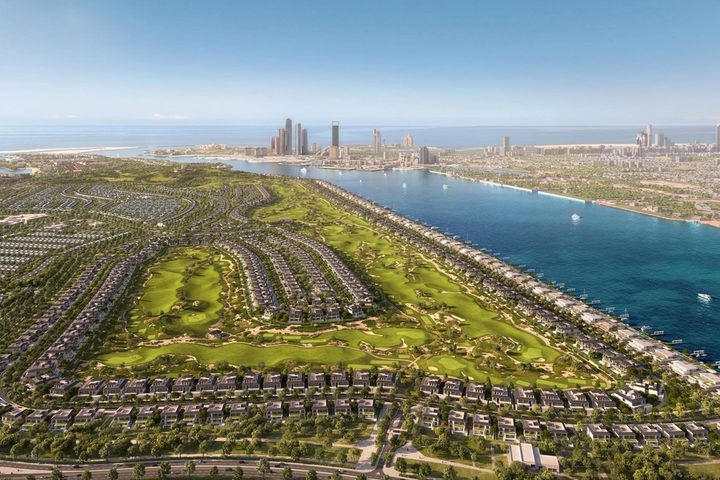
Hudayriyat Golf Estates offers homes from AED 4.25m to AED 35.55m. The developer, Modon, publishes a 40/60 plan with handover in Q3 2030. On a four-bedroom Golf Home from AED 7.35m, that is AED 2.94m paid during construction and AED 4.41m at handover.
Less of your own money is needed before handover, but a larger balance falls due at the end. That 60% is more than the 50% off-plan limit, so it only works with finance if a lender assesses the home as complete. At AED 7.35m, the most a bank could then lend is AED 4.41m (60%) if you live abroad or it is a second home: exactly the handover balance, with no margin if the valuation comes in lower.
In all three cases, any mortgage would be assessed against the lender's criteria at the time. These are illustrations, not a statement that finance is available for any of these homes. Prices and payment plans can change, and SPF can talk through the finance before you commit.
Funding the deposit from your UK home
For many buyers, the largest source of cash is not in the UAE at all. It is the equity built up in a home in the UK. SPF's UK business, SPF Private Clients Limited, advises on remortgaging a UK property to release money, and its UAE business can advise on a UAE mortgage if one is needed. The two are separate companies, regulated differently.
The worked examples above show why this matters. At Cedarwood Estates South, AED 1.335m is due on booking and AED 6.675m is paid before handover. At Hudayriyat Golf Estates, AED 2.94m is paid during construction on a four-bedroom Golf Home. On a completed home such as the Redwood Avenue villa, the deposit and purchase costs are due at transfer. Planning where that money comes from, before you reserve, keeps the timetable in your control.
Check this before you rely on it
UAE lending rules say a mortgage deposit should come from your own resources, not from other borrowing. If you also plan to take a UAE mortgage, ask SPF how the UAE lender will treat money released from your UK home before you rely on it for the deposit. The UK loan also counts towards the UAE affordability test.
Questions to talk through with SPF
What could I raise from my UK home, and what would the new UK repayments be?
Would a UAE lender accept released equity towards the deposit, and how would it count the UK repayments?
How would currency movements between sterling and dirhams affect the amount I have available?
Can the UK funds be in place in time for the booking payment, the instalments or the transfer date?
Releasing equity is subject to UK lender criteria and your circumstances. Any new UK borrowing is secured on your UK home. Think carefully before securing other debts against your home. If your income is in sterling and a UAE mortgage is in dirhams, exchange-rate changes can increase the sterling cost of your repayments.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Six steps to financing a UAE property
Every purchase is different, but the finance conversation usually follows the same six steps.
1. Set a working budget before you shortlist
Start with the cash you can commit and what a lender may be prepared to offer, then add purchase and registration costs. A conversation with SPF about your income, residency and existing commitments helps the shortlist reflect a realistic figure rather than a hopeful one.
2. Be clear about residency and income
Lender criteria can depend on where you live, how you earn and the currency you are paid in. Share these details with SPF at the outset, so its advice starts from your actual circumstances.
3. Prepare your documents early
Document requirements depend on the lender and on your circumstances, and identity checks form part of the process. Ask SPF for a checklist early, so nothing holds up the application once you have found the right property.
4. Obtain pre-approval, and read its conditions
Pre-approval can give you a firmer basis for making an offer, but it is conditional. It is not the same as a mortgage offer: final approval depends on an independent valuation, full documentation and the lender's assessment of you and the property. SPF says approval typically takes two to six weeks. Check what pre-approval assumes and whether it expires.
5. Match the finance to the purchase route
For a resale home, align the valuation and final offer with the agreed transfer date. For an off-plan home, use the payment plan to set out what you will fund yourself and what, if anything, finance may need to cover at handover.
6. Keep your adviser informed through to completion
A change of property, price, income or timetable can affect the lender's decision. Tell SPF promptly, so the application can be updated before it delays the purchase.
Six questions to ask SPF
-
What borrowing range is realistic for me?
Ask before you shortlist, so you view homes within a figure that reflects your income, residency and existing commitments.
-
Are my circumstances likely to suit lender criteria?
Where you live, how you earn and the currency you are paid in can all matter. Ask what could strengthen your application.
-
Which documents will I need, and in what form?
Request a checklist for your own situation, so paperwork does not hold up an offer.
-
What should I budget for beyond the deposit?
Include transfer and registration fees, valuation, legal and any advice fees, so the cash requirement is complete.
-
What does my pre-approval assume, and when does it expire?
Know what the lender still needs before final approval, and plan viewings and offers around it.
-
If I buy off-plan, when could mortgage finance be used?
Map the staged payments you would fund yourself until then, and what happens if your circumstances change before handover.
Frequently asked questions
Can non-residents get a mortgage in the UAE?
Often, yes, subject to the lender and your circumstances. SPF says finance for buyers who live outside the UAE is available subject to individual assessment, up to 60% of value, so plan on a larger deposit than a UAE resident would need. Ask SPF to look at your own position before you commit to a purchase.
Can I get a mortgage for an off-plan property?
Possibly, but UAE rules cap lending on off-plan property at 50% of value, and your own money is paid to the developer first. Off-plan purchases are paid for in stages, so the timing of any finance differs from buying a completed home. SPF can explain which options may be available for a specific development.
Can I use equity in my UK home to buy in the UAE?
Possibly, subject to UK lender criteria and your circumstances. SPF's UK business can advise on releasing equity from a UK property, and its UAE business on a UAE mortgage. UAE rules say a mortgage deposit should come from your own resources rather than other borrowing, so ask SPF how a UAE lender would treat released equity before you rely on it. Any new UK borrowing is secured on your UK home.
Is pre-approval the same as a mortgage offer?
No. Pre-approval indicates what a lender may be prepared to lend, subject to conditions. Final approval depends on an independent valuation, full documentation and the lender's assessment of you and the property.
Is SPF a lender?
No. SPF is a mortgage broker. It advises on mortgage options and supports your application to the lender. The lender makes the lending decision and sets its terms.
How does an introduction to SPF work?
Tell us about the property you are considering and the finance you may need. We will introduce you to SPF personally, so you can discuss your requirements with them directly. The introduction is optional, and you remain free to choose your own adviser.
Would you like to speak with SPF?
Whether you want to talk through a development or the finance, your enquiry comes to us first. Tell us the home you have in mind, and we will send current details and put you in touch with SPF.